Trust
The trust as a tried and tested instrument for protecting, structuring and passing on wealth
A trust is a written agreement between one or more settlors and one or more trustees. The settlor undertakes to transfer assets to the trustee, and the trustee undertakes to manage and utilise these assets in accordance with the provisions of the trust deed for the benefit of one or more third parties. The trust property does not constitute a separate legal entity; the trust is therefore not a legal person.
A trust is suitable for a wide range of asset and succession scenarios
Succession planning
Long-term planning for the succession of assets and businesses across generations.
Asset protection
Protecting and preserving assets across generations (asset protection).
Caring for relatives
Providing for and supporting family members or other individuals.
Non-profit status
Pursuing charitable objectives within a flexible trust structure.
Hold shareholdings
Holding and managing shareholdings, and supporting the companies in which it holds a stake.
International Tax Planning
Integration of trusteeship into cross-border asset structures.
Answers to the most important questions about Liechtenstein trusts
How does a trust come into being?
A trust may be established during the settlor’s lifetime or upon death. During the settlor’s lifetime, it is created by a written agreement between the settlor and the trustee. It may also be established by a unilateral written legal act or by a testamentary disposition; in the case of a unilateral declaration, a written declaration of acceptance by the trustee is also required.
What purposes can be pursued through a trust?
A trust may be established for various purposes. It may provide for the members of one or more families, aim to preserve and promote the businesses held by the trust, or serve charitable purposes.
Is the trusteeship entered in the Commercial Register?
Trust arrangements with a trustee resident or having their registered office in Liechtenstein, and lasting for more than 12 months, must be registered with the Commercial Register within 12 months of their establishment. Alternatively, an original or certified copy of the instrument of establishment may be filed with the Commercial Register without an entry being made in the register.
Who are the parties involved in the trusteeship?
The parties involved are the settlor, the trustee and the beneficiaries. The settlor may consist of one or more natural or legal persons who place assets into the trust. The trustee manages and utilises these assets; he or she may also be a natural or legal person. Beneficiaries are persons who derive a present or future benefit from the trust. A distinction is made between beneficiaries with a legal entitlement and discretionary beneficiaries, whose entitlement is at the discretion of the trustee or another party involved. In addition, a protectorate may be established comprising one or more persons appointed by the settlor.
What documents does the trusteeship hold, and what do they cover?
The trust deed sets out the terms of the trust. The trust property originally placed in trust and the beneficiaries are described either in the trust deed itself, in an annex thereto, or in a separate document such as supplementary provisions or regulations. The settlor may also draw up a ‘Letter of Wishes’ in which they set out their wishes regarding the trustee’s decisions. Whilst this is generally non-binding, it should be taken into account in the decision-making process.
Which assets can be transferred to the trust?
Movable and immovable assets may be transferred to the trustee. Rights and equity interests may also be contributed. There is no minimum asset requirement. As the trust does not have its own legal personality, the assets are transferred to the trustee, who is required to manage and utilise them in accordance with the purpose of the trust. Additional trust assets may be contributed at any time.
What rights and obligations does the trustee have?
The trustee must comply with the trust deed and the relevant statutory provisions, and must safeguard and manage the trust property. The trustee alone has the authority to manage and dispose of the trust property. The assets transferred to the trust must be kept separate from the trustee’s own assets, so that they remain recognisable as assets belonging to a separate legal entity. In the event of the trustee’s bankruptcy or enforcement proceedings against his assets, the trust property must be set aside by law and is thus protected from access by his creditors. The trust continues to exist irrespective of the identity of the trustee; should the trustee step down, another trustee may be appointed.
What rights does the settlor have?
Subject to any mandatory statutory provisions, the settlor is free to set out the terms of the trust in the trust deed. In particular, the settlor may reserve the right to revoke the trust or to amend the terms of the trust.
How long does the trusteeship last?
A trust may be established for a fixed or indefinite term. Unlike a common law trust, there is no limit on its duration; there is no ‘rule against perpetuities’.
When does the trusteeship come to an end?
A fixed-term trust relationship exists until the ground for termination specified in the trust deed occurs. If the settlor has reserved the right to revoke the trust, the trust relationship ends upon revocation. Furthermore, by operation of law, it ends if the trust property is lost.
How is a trust taxed?
The trust is subject only to the minimum income tax of CHF 1,800 per annum. This tax is payable regardless of the value of the trust assets or the income they generate. The transfer of assets to the trustee and distributions from the trust are tax-free in Liechtenstein, but may give rise to tax consequences abroad.
What are the reporting requirements?
Since 2017, Liechtenstein has been exchanging tax data with numerous countries under the Automatic Exchange of Information scheme. If the settlor has reserved the right to exercise influence through the trust arrangement, the total assets of the trust are generally reported to the settlor’s country of residence; in the absence of such rights, a report is made without specifying the assets. In the case of beneficiaries entitled to distributions, the attributable assets and distributions are reported; beneficiaries entitled to discretionary distributions are reported only in those years in which they have actually received distributions. If the trust has one or more protectors with the right to exercise influence, the total assets are also reported to their country of residence.
What you stand to gain, specifically
A flexible structure on a contractual basis without the trust assets becoming legally separate.
The company may be incorporated without any statutory minimum capital requirement.
The trust property is separate from the trustee’s assets and protected from the trustee’s creditors.
Rights of revocation, rights to make changes and a ‘Letter of Wishes’ allow for a personalised arrangement.
The trusteeship continues regardless of the individual trustee.
A minimum income tax of just CHF 1,800 per annum in Liechtenstein.
Why Kaiser Partner
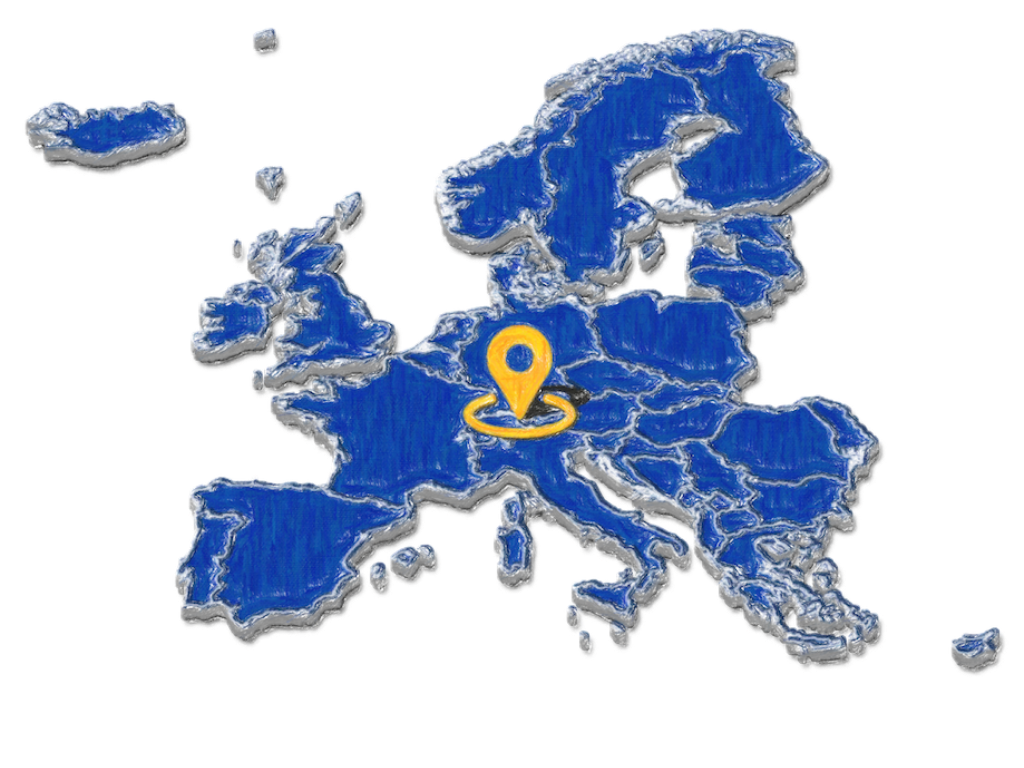
Liechtenstein has one of the oldest and most stable sets of company laws in Europe. The Law on Persons and Companies (PGR) of 1926 forms the basis for structures that offer long-term reliability – whether a foundation, trust, public limited company or Anstalt – regardless of political developments in other countries.
Kaiser Partner Wealth Advisors has specialised in the structuring of cross-border assets for decades. Its headquarters in Vaduz, Liechtenstein, is no coincidence, but rather a structural advantage.
Setting out the intended purpose, the beneficiaries and the settlor’s intended rights of control.
Definition of the roles of the settlor, trustee, beneficiaries and, optionally, a protectorate.
Drafting of the trust deed and any supplementary statutes, regulations and a letter of wishes.
Transfer of the assets to the trustee and, where applicable, registration or filing with the Companies Register.
Administration of the trust assets in accordance with their intended purpose, and fulfilment of tax and reporting obligations.